Buying a home is one of the biggest investments you will ever make. Knowing if a house is in a flood zone can save you from costly mistakes. According to the Federal Emergency Management Agency, nearly 13 million Americans live in high-risk flood areas. Flooding causes billions in damages annually, making this check essential for every homebuyer.
Why Checking Flood Zones Matters
Flood zones indicate areas prone to flooding based on historical data. Homes in these zones often require costly flood insurance. Insurance premiums can add thousands to your annual expenses. Lenders may also demand additional protections before approving a mortgage.
Flood damage is not covered by standard homeowners insurance policies. Without proper coverage, you could face financial ruin after a disaster. Knowing the risk helps you budget for insurance and repairs. It also gives you leverage to negotiate a better price.
Some flood zones have building restrictions to reduce damage. These rules can limit renovations or expansions. Ignoring them may lead to fines or legal issues. Understanding these constraints helps you plan for the future.
Flood risks can also affect your home’s resale value. Buyers often avoid properties in high-risk areas. Disclosing flood risks upfront builds trust with potential buyers. It also prevents legal disputes later on.

Official Tools to Check Flood Zones
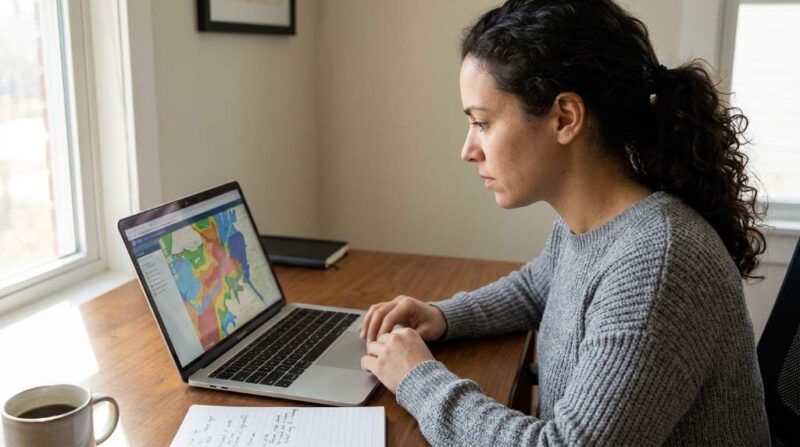
The FEMA Flood Map Service Center is the most reliable resource. It provides interactive maps showing flood zones across the United States. You can search by address to see if a property is in a high-risk area. The maps are updated regularly to reflect changing conditions.
FEMA maps use different letters to classify flood risks. Zones labeled A or V are high-risk areas. These zones have a 1 percent chance of flooding each year. Zones labeled B, C, or X are moderate to low-risk areas.
To use the FEMA tool, enter the property address in the search bar. The map will highlight the flood zone for that location. You can zoom in for a closer look at the boundaries. Print or save the map for your records.
FEMA also offers a Flood Factor tool in partnership with the First Street Foundation. This tool provides a more detailed risk assessment. It includes projections for future flooding due to climate change. The Flood Factor assigns a score from 1 to 10 based on risk levels.
Local Resources for Flood Zone Information
Your city or county planning department can provide flood zone data. They often have maps and reports specific to your area. Local officials can also explain building codes and restrictions. These rules may affect your plans for the property.
Many communities participate in the National Flood Insurance Program. This program offers affordable flood insurance to residents. Local officials can tell you if your area is part of the program. They can also provide information on flood preparedness and mitigation.
Real estate agents and sellers must disclose known flood risks in many states. Ask for a flood history report for the property. This report will show past flooding events and insurance claims. Reviewing this information can reveal hidden risks.
Local utility companies may also have flood-related data. They track flooding that affects infrastructure like water and electricity. Contact them for additional insights. This information can help you assess the property’s vulnerability.
How to Read Flood Zone Maps
Flood zone maps use colors and labels to indicate risk levels. High-risk areas are typically shaded in blue or red. Moderate to low-risk areas may be shaded in yellow or green. Each color corresponds to a specific zone designation.
Zone A indicates areas with a 1 percent annual chance of flooding. These areas are also known as 100-year flood zones. Zone V indicates coastal areas with a high risk of flooding. These zones are subject to additional building requirements.
Zone B and Zone X indicate areas with a moderate to low risk of flooding. These areas are outside the 100-year flood zone. However, they may still experience flooding under certain conditions. Always check the map legend for details.
Flood maps also show base flood elevations for certain zones. These elevations indicate the height floodwaters are expected to reach. Comparing the base flood elevation to the property’s elevation can help you assess risk. Properties below the base flood elevation are at higher risk.
Red Flags to Watch For
Properties near rivers, lakes, or coastlines are more likely to flood. Even homes not directly on the water can be at risk. Check the property’s proximity to these features on the map. Also, look for drainage ditches or retention ponds nearby.
Low-lying areas are more susceptible to flooding. If the property is in a valley or depression, it may collect water. Drive by the property after heavy rain to see if water pools. Standing water is a clear sign of poor drainage.
Neighboring properties can also provide clues about flood risk. If nearby homes have experienced flooding, yours likely will too. Ask neighbors about their experiences with flooding. They can offer firsthand insights into the area’s vulnerability.
Check for water stains or mold in the basement or crawl space. These signs indicate past flooding. Also, look for sandbags or flood barriers around the property. These measures suggest the owner has dealt with flooding before.
Review the property’s elevation certificate if available. This document provides detailed information about the property’s elevation. It also includes flood zone data and base flood elevations. The certificate is often required for flood insurance.
Unique Considerations for Different Regions
Coastal areas face unique flood risks from storm surges and hurricanes. These events can cause catastrophic flooding even in low-risk zones. Check for additional maps specific to coastal flooding. Also, consider the impact of sea-level rise on future risk.
Inland areas may experience flash flooding from heavy rainfall. This type of flooding can occur quickly and without warning. Check local weather patterns and historical data. Areas with frequent thunderstorms may be at higher risk.
Urban areas often have poor drainage due to impervious surfaces. This can lead to localized flooding during heavy rain. Check the property’s drainage system and the surrounding infrastructure. Poor drainage increases the risk of water damage.
Rural areas may have different flood risks due to natural features. Rivers, streams, and wetlands can all contribute to flooding. Check the property’s proximity to these features. Also, consider the impact of land use changes on flood risk.
What to Do If the House Is in a Flood Zone
If the property is in a high-risk flood zone, consider purchasing flood insurance. The National Flood Insurance Program offers policies for eligible properties. Private insurers may also offer flood coverage. Compare quotes to find the best option.
Flood insurance premiums vary based on the property’s risk level. High-risk zones have higher premiums. However, even low-risk properties can benefit from coverage. Flood insurance can provide peace of mind and financial protection.
Mitigation measures can reduce flood risk and insurance premiums. Elevating utilities, installing flood vents, and waterproofing basements can help. Consult a professional to determine the best measures for your property. These improvements can also increase your home’s value.
If the property is in a high-risk zone, consider negotiating the price. Use the flood risk as a bargaining chip to lower the purchase price. You can also ask the seller to cover the cost of flood insurance for the first year. This can offset some of the additional expenses.
Before purchasing, consult with a real estate attorney. They can review the property’s flood history and disclosure documents. They can also explain the legal implications of buying in a flood zone. This step ensures you make an informed decision.
Common Misconceptions About Flood Zones
Many people believe flood zones only apply to coastal areas. However, flooding can occur anywhere, even in landlocked states. Inland flooding from rivers, lakes, and heavy rainfall is common. Always check the flood risk regardless of the property’s location.
Another misconception is that flood insurance is only for high-risk zones. In reality, about 25 percent of flood claims come from low to moderate-risk areas. Flood insurance can provide valuable protection for any property. It is an important consideration for all homebuyers.
Some buyers assume that homeowners insurance covers flood damage. This is not true in most cases. Standard policies typically exclude flood damage. Separate flood insurance is required to cover these losses. Do not assume you are protected without verifying your coverage.
People also believe that flood zones never change. However, flood maps are updated regularly to reflect new data. Climate change, development, and other factors can alter flood risks. Always check the most recent maps for accurate information.
Conclusion
Knowing if a house is in a flood zone is essential for every homebuyer. It helps you avoid costly surprises and make informed decisions. Use the tools and resources provided in this guide to assess flood risk. Take action to protect your investment and ensure your family’s safety.
Do not let flood risks deter you from buying your dream home. With the right knowledge and preparations, you can manage these risks effectively. Start by checking the flood zone for any property you are considering. Then, take steps to mitigate the risks and secure proper insurance.
If you are unsure about the flood risk, consult with a professional. Real estate agents, insurance providers, and local officials can offer valuable insights. They can help you understand the risks and make the best decision for your situation.
Take the time to research and prepare before buying a home. Your due diligence will pay off in the long run. It can save you money, stress, and heartache. Make flood zone checks a standard part of your homebuying process.
FAQs
How do I check if a property is in a flood zone?
Use the FEMA Flood Map Service Center or consult local planning departments for accurate flood zone information.
Does homeowners insurance cover flood damage?
No, standard homeowners insurance policies do not cover flood damage; separate flood insurance is required.
Can flood zones change over time?
Yes, flood zones are updated regularly based on new data, climate change, and development.
What should I do if a house is in a high-risk flood zone?
Consider purchasing flood insurance, implementing mitigation measures, and negotiating the purchase price.
Are there flood risks in inland areas?
Yes, inland areas can experience flooding from rivers, lakes, heavy rainfall, and poor drainage.